87% finish the 10-step tutorial; 12% finish the 10-step claim
Why 87% finish a bank's 10-step tutorial but only 12% finish its 10-step claim, and what that gap reveals about process design
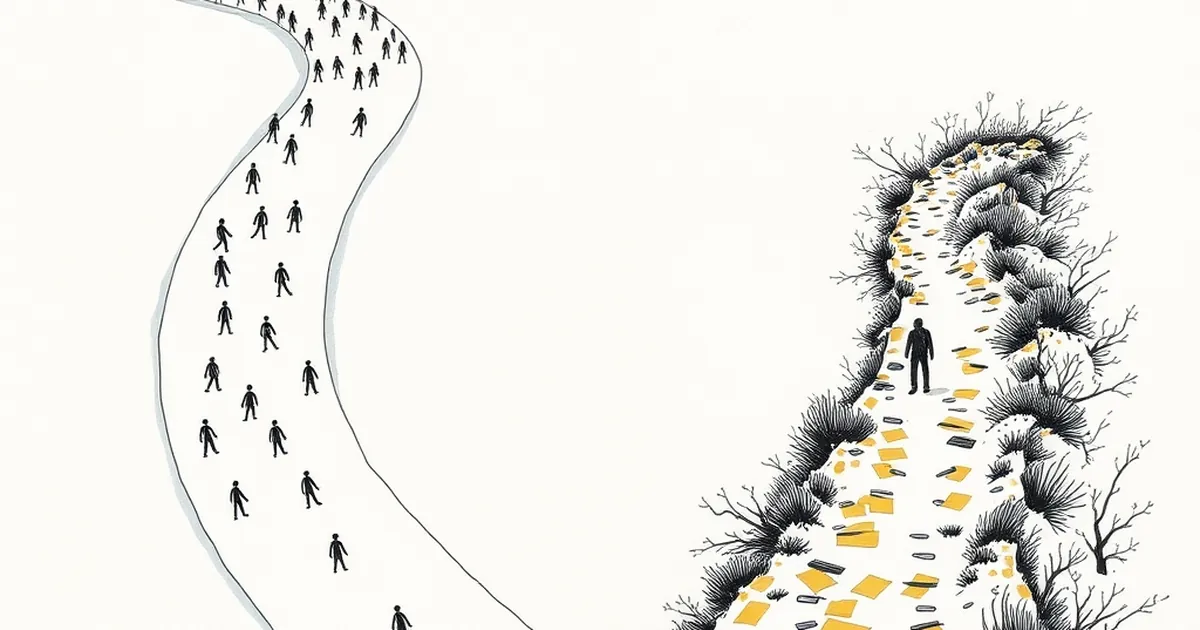
Picture two funnels side by side. On the left, a bank onboards a new customer through a ten-step digital tutorial: verify identity, link an account, set a PIN, enable notifications, and so on. Eighty-seven percent of people who start that tutorial finish it. On the right, the same customer, months later, opens a claim on a payment that went wrong — a chargeback, a disputed transfer, a missing refund — and faces a ten-step process that looks, structurally, almost identical. Only twelve percent finish. Same bank, same app, same ten steps. So what actually changes between the left funnel and the right one?
Two funnels, one architecture, opposite outcomes
The gap between 87% and 12% isn't a story about interface design. It's a story about what the user believes is waiting at the end of each step.
In the tutorial, every completed step produces a small, immediate, legible reward. The progress bar moves. A checkmark appears. The app says "you're three steps from being done." The user can see the finish line, and the finish line is a version of themselves with more capability than they had five minutes ago.
In the claim, the reward structure inverts. Every completed step produces uncertainty. The user fills in a reference number and doesn't know if it's the right one. They upload a receipt and don't know if a screenshot will be accepted. They wait three days for a status update that says "under review." The progress bar moves, but the user has no idea whether progress means anything — whether they're three steps from a refund or three steps from another rejection letter.
Behavioral economists have a name for what's happening here, and it isn't complicated. It's the difference between a task with a visible terminal state and a task with an invisible one. The tutorial has a terminal state the user can picture. The claim doesn't.
What Kahneman and Tversky would say about step seven
Loss aversion is one of the most replicated findings in behavioral economics, and it's usually summarized as "losses loom larger than equivalent gains." Kahneman and Tversky's original framing, from their 1979 prospect theory paper, is more precise: people don't weigh outcomes in absolute terms. They weigh them relative to a reference point, and they're roughly twice as sensitive to movement below that reference point as above it.
For a tutorial, the reference point is "I don't know how to use this feature." Every step moves the user above their reference point. That's a gain frame, and gains feel good enough to sustain effort.
For a claim, the reference point is "I had money and now I don't." The user is already below their reference point before the process starts. Every step is an attempt to climb back to where they started — not to gain something, but to undo a loss. And climbing back to zero is psychologically exhausting in a way that climbing above zero isn't. The user isn't working toward a reward. They're working toward the absence of a penalty they never agreed to.
This is why "just make the claim process easier" doesn't solve the problem. You can reduce the claim from ten steps to five and still lose most users at step two, because the issue isn't step count. It's that every step in a claim is a step taken under uncertainty, and uncertainty itself is a cost.
The variable-ratio problem hiding in your claims queue
There's a second dynamic at work, and it's less discussed in banking circles than it should be.
Variable-ratio reinforcement — the principle that intermittent, unpredictable rewards produce more persistent behavior than predictable ones — is usually invoked to explain why people keep pulling a lever or refreshing a feed. But it cuts the other way too. Intermittent, unpredictable punishments produce rapid extinction of behavior. If a user submits a claim and gets a refund, then submits another and gets denied, then submits a third and gets a partial refund, the pattern teaches them something specific: this process is not reliably in my favor.
Once that lesson lands, the user doesn't just abandon the current claim. They stop opening claims altogether. They eat the loss. They switch to a different payment method for high-stakes transactions. They tell three friends. The 12% completion rate isn't a snapshot of one bad process — it's the visible edge of a much larger behavioral shift that's already happened upstream.
A concrete case: the UK's chargeback reform
In 2018, the UK's Financial Conduct Authority extended chargeback rights to faster payments — bank transfers, not just card transactions. Before the change, a customer who'd been tricked into sending money to a fraudster had almost no recourse; the money was gone, and pursuing it meant navigating a process most people didn't know existed. After the change, banks were required to reimburse victims of authorized push payment fraud, subject to a claims process.
The interesting part isn't the policy. It's what happened to claim volume. When the process became more predictable — clearer eligibility rules, a defined reimbursement standard, an expectation of a decision within a set window — the number of people who initiated claims rose sharply. Not because fraud increased dramatically, but because the expected value of starting a claim changed. Users no longer had to guess whether the effort would pay off.
That's the lesson banks keep rediscovering. Completion rates aren't driven by friction. They're driven by whether the user can predict the outcome.
Designing for the twelve percent
So what would move the needle on the right-hand funnel?
The most effective intervention isn't shortening the form. It's making the outcome legible before the user starts. A claim process that opens with "here's what qualifies, here's what doesn't, here's the decision timeline, here's the likely outcome for your situation" will outperform a shorter process that leaves the user guessing. Predictability is the reward. The refund is just the confirmation.
The second intervention is closing the loop at every step, not just the last one. If a user uploads a receipt, tell them immediately whether it's acceptable — not three days later. If a reference number is wrong, say so at the moment of entry. Every silent step is a step where the user's mental model of "am I going to get my money back" drifts toward no.
The third, and hardest, is treating the claim as a customer relationship event rather than a compliance event. The 87% who finish the tutorial finish because someone designed the experience around their confidence. The 12% who finish the claim finish despite the fact that no one did.
The forward-looking question for every payments team isn't "how do we reduce claim volume?" It's "how do we make the claim process feel like the tutorial — a sequence of small, certain, visible wins?" Because the user who finishes a claim is the user who trusts the next transaction. And the user who abandons one is already halfway to a different provider.