Reward tiers at 80% feel closer than 20% left to clear
Framing progress as 80% complete rather than 20% remaining changes how consumers feel about reward tiers, with real implications for card and wallet design
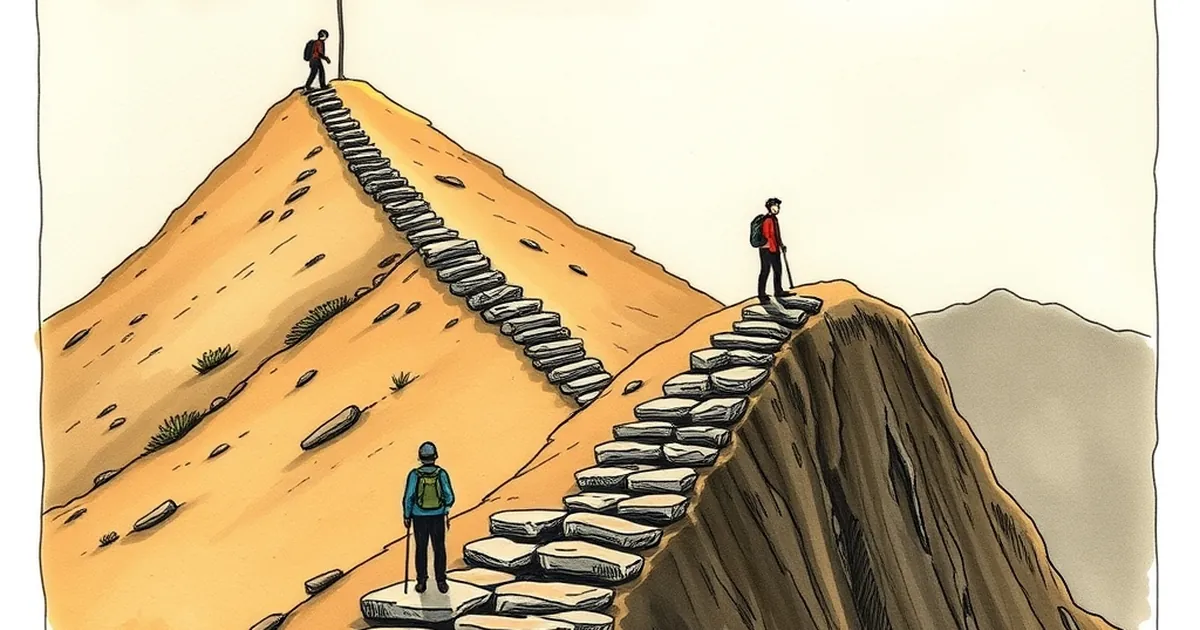
Think about the last time a loyalty program told you that you were "80% of the way to Gold status." Did it feel like a win, or did it feel like a bill you hadn't paid yet? The answer probably depends less on the math than on how the number was framed — and that framing gap is one of the most quietly powerful levers in consumer payments. If reward tiers at 80% complete feel closer than tiers at 20% remaining, what does that tell us about how card issuers, wallets, and merchant apps should be designing progress?
The Same Gap, Two Different Feelings
A tier that requires $10,000 in annual spend, with $8,000 already logged, is 80% complete and $2,000 short. A tier that requires $10,000, with $2,000 already logged, is 20% complete and $8,000 short. Nobody confuses these. And yet the first one reliably produces more engagement, more "I'm almost there" behavior, and more willingness to route the next purchase to that card.
This is not a rounding error in human cognition. It's a well-documented asymmetry. Kahneman and Tversky's work on prospect theory established that people evaluate outcomes relative to a reference point, and that losses loom larger than equivalent gains. A tier target is a reference point. When you've banked 80% of the distance, the remaining 20% is framed as something you're about to gain. When you've banked 20%, the same target reads as a distant obligation — and the effort to close an $8,000 gap feels disproportionate to the reward.
There's a second mechanism at work: the goal-gradient effect, first described by Clark Hull in the 1930s and later demonstrated in consumer settings by Ran Kivetz, Oleg Urminsky, and Yuhuang Zheng in a 2006 Journal of Marketing Research study on coffee cards and reward programs. Their finding, in plain terms: effort accelerates as people approach a reward. A loyalty card with 10 stamps needed and 8 already filled gets punched faster than one with 2 filled. The card is identical. The perceived distance is not.
Why "80% There" Beats "20% Left" in Card Programs
Issuers have known this intuitively for years, which is why so many programs show you a progress bar rather than a dollar figure. But the design choices go deeper than a bar.
Consider how welcome bonuses are typically structured. A new cardholder is told they'll earn a sign-up bonus after spending $4,000 in the first three months. Framed as "you've unlocked $3,200 of your $4,000 target," the remaining $800 feels like a short sprint. Framed as "you need $4,000 in spend," the whole thing reads as a hurdle. The first framing converts; the second gets abandoned. Same offer, same terms, different psychology.
The asymmetry also shapes how people respond to tier demotion. American Express, Chase, and a range of hotel and airline co-brands have all experimented with soft-landing language — "you're $1,200 from keeping your current tier" — precisely because the threat of losing status is more motivating than the promise of gaining it. That's loss aversion doing the work, and it's why "you have 20% left to retain Gold" outperforms "you need 80% more to reach Platinum" for the same customer in the same position.
The midpoint problem
There's a wrinkle worth naming: the effect is weakest in the middle. At 50% progress, neither the "almost there" nor the "still far" frame dominates, and engagement often plateaus. Programs that front-load progress — a welcome bonus that immediately credits a chunk of tier progress, or a "head start" status match — are effectively buying past the midpoint problem. They move the customer into the zone where the goal-gradient effect starts pulling.
What This Means for Decision-Making Under Uncertainty
Reward tiers are a small, controlled version of a much larger question: how do people decide whether to keep investing in something? The behavioral literature on sunk cost and escalation of commitment suggests we're not great at it. We keep spending on a card because we've already spent, not because the marginal reward justifies it.
That's the risk side of this coin. A progress bar at 80% can tip a rational "this card no longer suits my spending" into an irrational "I'm too close to quit." Issuers know this, and a well-designed program should be honest about it. The better programs — and there are a few — let you see the full math, not just the flattering frame. They show the remaining spend in currency, not just a percentage, so the customer can decide whether the last 20% is worth chasing.
Variable-ratio reinforcement, the schedule that makes unpredictable rewards so sticky, shows up here too. Some programs randomize bonus categories or surprise multipliers. That unpredictability keeps people checking the app, but it also makes it harder to plan. The tension between "engaging" and "manipulative" is real, and it's the thing regulators are starting to look at more closely in markets from the UK to Australia.
A Concrete Example: The Coffee Card That Started It All
The Kivetz, Urminsky, and Zheng study is worth revisiting because it's so clean. Customers given a loyalty card requiring 10 purchases, with 2 already credited, were compared against customers given a card requiring 12 purchases with 2 already credited — but the second card included 2 "bonus" stamps. Both groups faced the same real requirement: 10 more purchases. The group with the bonus stamps, who perceived themselves as further along, completed the card faster and were more likely to redeem.
The lesson transfers directly to payments. A cardholder told "you're 8 of 10 purchases into your bonus" behaves differently from one told "you need 10 more purchases," even when the underlying distance is identical. The frame is the product.
Where This Goes Next
The interesting frontier isn't better progress bars — it's personalized framing. If a customer's spending pattern suggests they'll clear a tier comfortably, telling them "80% there" is honest and motivating. If their pattern suggests they won't, the same message becomes a pressure tactic that erodes trust. The programs that get this right will use the asymmetry to inform rather than to nudge into overspending, and they'll be rewarded with customers who stay longer because they feel respected, not cornered.
For anyone building in this space, the practical takeaway is to audit your progress language the way you'd audit a fee disclosure. Ask: does this frame help the customer make a better decision, or does it just make them feel closer to something they can't quite reach? The answer will differ by customer, by product, and by market — and getting it right is the next real differentiator in a category where the underlying rewards are increasingly commoditized.